When selling a home, evaluate the strength of a written offer using its price, terms, funding, and deadlines. Enthusiasm at a showing does not establish whether a transaction will close.
Representation, financing, and price each raise useful questions. None should be used alone to label a buyer as serious or unserious.
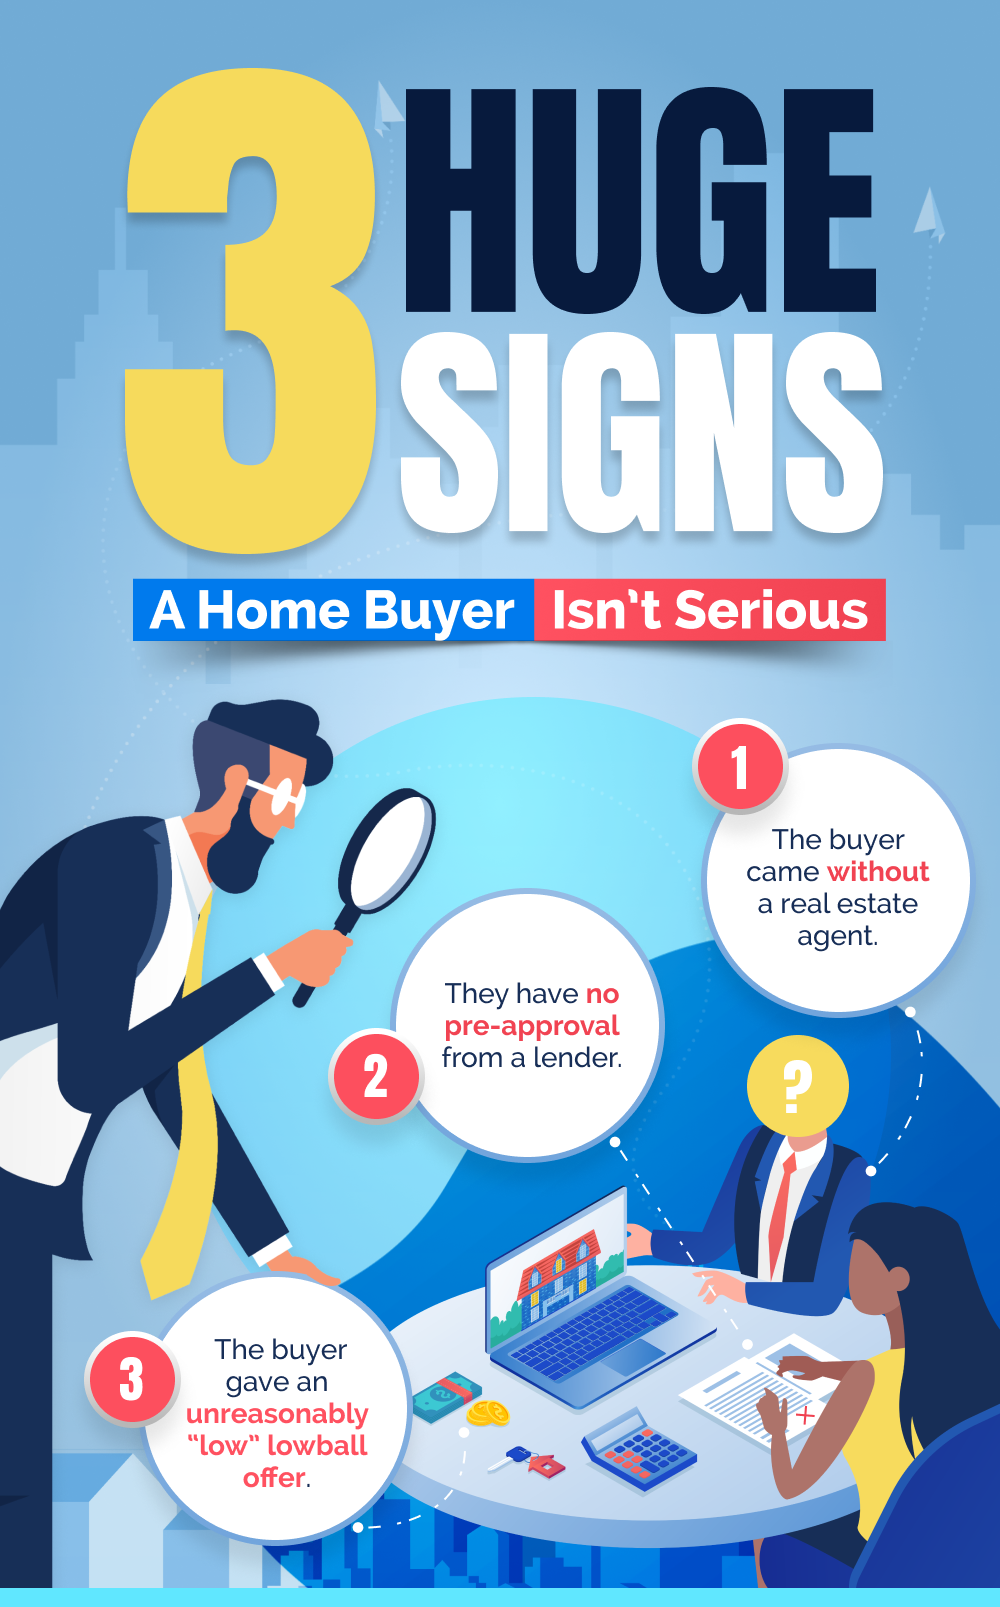
Use the three checks below with your agent, lender, title professional, or attorney as appropriate. The goal is to understand the evidence and risks before accepting an offer.
1. Clarify representation and communication.
A buyer may attend a showing with or without representation. Compensation is negotiable and should be documented in the applicable agreements; buyer representation is not automatically free. See NAR guidance on negotiating buyer agreements. Evaluate the actual offer and funding information rather than assuming that an unrepresented buyer is not serious.
Content clarification: September 27, 2026. The original publication date is retained.
Clarify who represents each party and how communications and required documents will be handled. An unrepresented buyer may still make a credible offer; the signed terms and ability to perform matter.
2. Review the funding evidence and conditions.
For a financed offer, review the lender letter, proposed loan type, financing contingency, and relevant deadlines. Pre-approval is conditional and is not a guarantee that the loan or property will receive final approval. For a cash offer, appropriate proof of funds may be relevant instead.
Ask your agent to help identify what the funding documents establish, what remains subject to review, and what information may need to be confirmed with the buyer's lender. Avoid sharing unnecessary account details.
3. Evaluate price together with the other terms.
A low offer does not establish that a buyer is insincere. Compare the price with current comparable sales and consider concessions, contingencies, closing timing, and the estimated net proceeds.